Market Recap
On the surface, the third quarter looks unremarkable. The U.S. stock market returned 2.3% and is 12.7% higher for the year, with record highs set along the way. Beneath that modest move, however, was a bond market that took over the narrative. The Federal Reserve raised interest rates for the first time in more than three years, long-term Treasury yields pushed to levels last seen two decades ago, and oil rose by more than a third as the war with Iran reignited. The quarter’s internal story was one of divergence. The Nasdaq Composite gained 2.6% and set a record above 27,244 in late September. The Dow Jones Industrial Average, by contrast, fell 2.3%, and small company stocks fell 7.2%. International equity markets fared worse in large part thanks to a stronger dollar. Sector returns paint an interesting story. As yields surged in September, the financial sector fell more than 7%, its worst month since early 2023, while energy rode the oil shock higher over the quarter and technology benefited from AI optimism. The market began the year broadening out but spent much of the third quarter re-concentrating. The market-cap weighted S&P 500 was flat in September whereas the equal-weighted version fell 4.8%, and the former is now ahead of its equal-weighted counterpart for the year. Just two of the 11 sectors have year-to-date returns higher than the overall index.
The U.S. economy continues to grow and outpace expectations. The labor market stumbled over the summer, with a combined 52,000 jobs added in June and July, but August saw payrolls rebound by 162,000 against expectations of roughly 55,000, while the unemployment rate held at 4.1%. Growth was revised higher for the second quarter, to 2.2% from 1.5%, and for the first quarter, to 2.5% from 2.1%. The economy is being powered in no small part by the largest capital-spending boom in modern history. That resilience is welcome news for earnings, but it is considerably more complicated for the direction of interest rates.
The AI trade traveled a real arc this quarter, from unraveling in July to a sharp revival in September. A crowded, leveraged position held by a well-known AI hedge fund triggered a sharp drawdown in July as small losses cascaded, and investors who had spent years rewarding ever-larger capital-spending commitments abruptly began punishing them. Alphabet fell more than 7% on results that beat expectations because its capex guidance jumped, and Meta was treated similarly. Technology stocks slid into their second correction of the year. But once positions were reset, the sector climbed 16.2% from its late-July low into quarter-end and is now up 28.4% for the year, behind only energy.
Economic & Investment Outlook
On September 16th, the Federal Open Market Committee raised the federal funds rate by a quarter point to a range of 3.75% to 4%. It was the first increase in more than three years, and it partially reverses the easing cycle of late 2025. Contrary to many expectations prior to his appointment, Fed Chair Kevin Warsh has taken a hawkish stance on inflation and has departed from the Trump administration’s desire to lower rates. Hawkish projections appeared in June, the Committee split 9–3 in July with three dissents in favor of a hike, and at Jackson Hole in August Warsh declared bluntly that the Fed had work to do.
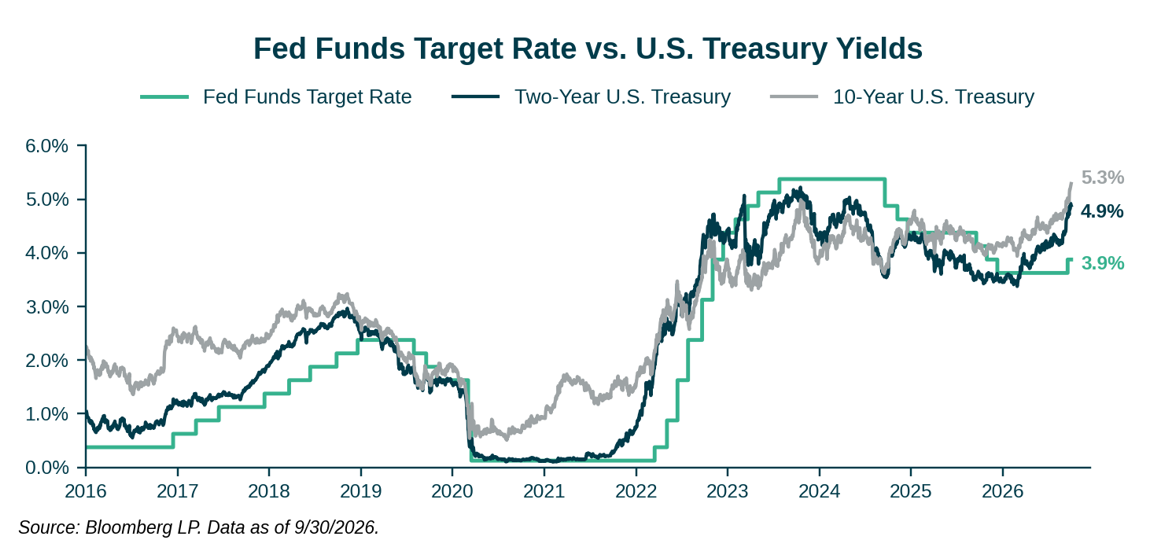
The vote deserves as much attention as the move. The September hike passed twelve to zero, a unanimous decision from a Committee that was fractured two months earlier, and over the explicit objections of the White House. Whatever one thinks of the policy, the signal is clear: this Fed has united around the view that the inflation fight is unfinished. The projections sharpened the message. The median projection for the funds rate at year-end rose to 4.1%, implying at least one more hike at one of the two remaining meetings, and the 2027 median sits at the same level, pointing to rates that go up and stay higher rather than a quick round trip.
The Fed delivered its most hawkish act in years into inflation data that promptly cooled, albeit partly because of methodology changes. The Bureau of Economic Analysis’s annual revisions, released in September’s final week, rewrote how several categories of services inflation are measured and applied the changes retroactively across five years. July’s core PCE reading was revised to 3.0% from 3.3%, and August held at 3.0% compared to expectations above 3.3%, while headline inflation came in at 3.4%. Even the friendlier methodology leaves core inflation a full point above the 2% target, with services categories near 4%, and September’s data will carry the surge in oil prices.
The bond market repriced at the long end. The 10-year Treasury yield ended the quarter at 5.29%, within sight of its 2007 highs, after rising more than half a percentage point in September alone. The 30-year closed at 5.63%, a level last seen in 2002. A majority of respondents to a late-September Bloomberg survey expect it to trade above 6% before year-end. The curve bear-steepened over the quarter, with long-term yields rising more than short-term yields.
We are not convinced this is only about inflation. Long-term inflation expectations, measured by market breakevens, remain reasonably anchored, and the move has overwhelmingly been in real yields. The economy is simply running hotter than the consensus believed, with nominal growth around 7% and the major technology platforms deploying roughly $600 billion of capital spending this year, mostly on AI infrastructure. Supply is adding pressure as well. The federal deficit is running at around $2 trillion, slightly more than 6% of GDP, and the same AI buildout is increasingly financed in the bond market. According to BCA Research, AI-related debt now makes up more than 30% of net Treasury issuance. Every dollar absorbed by hyperscaler debt is a dollar not bidding for Treasuries. This should force yields higher to clear the market. Stack those up and it’s not much of a mystery why rates are touching multi-decade highs. We don’t think anything is broken. The economy is currently able to handle a higher cost of capital, and markets are repricing.
Portfolio Positioning
As for the positioning of portfolios, within equities we reduced our emerging market exposure during the quarter as a way to diversify our equity exposure away from AI related sectors and countries. Given the tremendous growth in AI, markets are becoming increasingly concentrated in those names (i.e. – Taiwan Semiconductor/TSM makes up over 17% of the emerging market stock index). This is just a prudent risk reduction measure. As for bonds, the front and belly of the curve now offer yields near or above 5% with far less sensitivity to the forces pushing the long end higher. This is where our bond portfolios are more concentrated. We are taking less duration and picking up attractive yields of 5-6%, and while there will be a case for extending duration, we remain comfortable with current positioning. These higher yields bode well for future returns for our balanced portfolios. Finally, we maintain positions in real estate and alternatives, including trend-following managed futures funds. We believe they offer long-term portfolio benefits in providing alternative and non-correlated returns relative to traditional stock and bond holdings. They can perform well whether the macro backdrop is deflationary, inflationary, stagflationary, etc. Our conviction in owning these strategies remains high.
Closing Thoughts
The fourth quarter arrives with a full calendar. Third-quarter earnings season begins in mid-October. The Federal Reserve meets October 27–28th, a week before the midterm elections on November 3rd, and again in early December. The continuing resolution that averted a government shutdown funds the government only through December 11th.
On the Fed, the market enters the quarter pricing an October pause as slightly more likely than not and a December hike as the base case. That would be our base case as well. The softer late-September inflation data took some of the urgency out of an October hike, and the proximity of the midterms argues against politicizing any move. We would not expect a pivot to easing on any horizon. This Fed has told us its priority is inflation and acted on it.
On the midterms, we will keep our thoughts brief. Betting markets currently favor the Democrats in both chambers. Markets have historically been comfortable with divided government, which tends to freeze the policy status quo, and either controlling party has been happy to spend. With the deficit and the long end of the yield curve now central to the outlook, the election’s most important market consequence may be what it signals about the fiscal trajectory. We will be watching the bond market’s reaction more closely than the stock market’s. Beyond that, we hold to our long-standing view: portfolios should not be positioned on political predictions. Vote at the polls, not in your portfolio.
We thank you for your continued trust and partnership. Please also find enclosed the economic newsletter from Dr. Ray Perryman.
The Water Valley Investment Team